Table of Contents
Tax on rental income is charged on profit, not the full rent received. Profit is the rental income after allowable expenses and relevant reliefs. The calculation becomes more complicated when mortgage interest, repairs, joint ownership, overseas landlords or multiple properties are involved.
ONS reported average private rent in London at £2,294 in May 2026, the highest regional average in Great Britain. That figure is useful context, but landlords still need property-level evidence because rent, demand and affordability can vary sharply between neighbouring boroughs and even between streets. The source for that market context is the ONS private rent and house price bulletin.
The safest way to approach tax on rental income is to look at the rule, the money and the evidence together. A landlord may start with one practical question, but the answer often depends on several connected points: rental profit, tax bands and mortgage interest. Treating those points separately is how mistakes creep in. The better approach is to decide what needs to be checked before the tenancy or transaction starts, what should be recorded during the arrangement, and what evidence will be needed if the decision is challenged later. That gives the landlord a clearer route from general information to a property-specific decision.
That is why timing matters. Checking the point before a tenancy starts is usually cheaper and simpler than trying to correct it after a dispute, claim, licence query or tax deadline has appeared. A landlord should also think about who will need the evidence later: a tenant, buyer, lender, insurer, council officer, tribunal, accountant or managing agent. The same document can serve several purposes if it is kept properly. A clear rent record can support a tax return and an arrears claim. A dated photograph can support a deposit deduction and a repair history. A certificate can help with compliance and reassure a buyer. Treating records as part of the management system rather than a last-minute admin task makes the property easier to own.
A simple example shows why this matters. A landlord may think the issue is only about one decision, such as a deduction, licence, insurance clause, rent increase or repair. In reality, that decision can affect several later steps. The same facts may decide whether the tenant accepts the position, whether a council sees the property as properly managed, whether an insurer accepts a claim, whether a buyer proceeds, or whether an accountant can defend the treatment in the accounts. When the record is complete, those later conversations are shorter and less risky.
Rental profit is the taxable figure
A landlord who receives £1,600 pcm does not necessarily pay tax on £19,200. Allowable expenses may include management fees, repairs, insurance, service charges, accountancy and other costs incurred wholly and exclusively for the rental business.
The AMS guide to landlord costs is useful when building a realistic net-income forecast before deciding whether to self-manage, use an agent or consider guaranteed rent.
This part of the decision should be written down rather than left as a verbal understanding. For a landlord, the risk usually appears later: when a tenant challenges a charge, a council asks for evidence, an insurer reviews a claim, or HMRC queries a figure. Keep taxable profit, allowable expenses, evidence for HMRC and the date money was received or deducted in the same property file so the decision can be reconstructed months or years later. HMRC’s Income Tax rates and allowances and property income guidance should be checked before filing, because the tax position depends on total income and allowable costs, not rent received alone.
The starting point is to match rent receipts to the right tax treatment. Overseas status, agent deductions, management fees, repairs and finance costs should all be visible in the records, because HMRC will expect the landlord to explain the difference between rent collected and profit declared.
For tax on rental income, the first step is usually to define the position precisely. Vague words create later disagreements: ‘managed’, ‘reasonable’, ‘included’, ‘market rent’ and ‘good condition’ can mean different things to different people. The practical answer is to translate those broad words into evidence, dates, responsibility and cost. The same discipline applies in the property file. If the landlord can point to a clause, certificate, valuation, photograph or dated message, the decision becomes much easier to defend.
Income tax bands for 2026/27
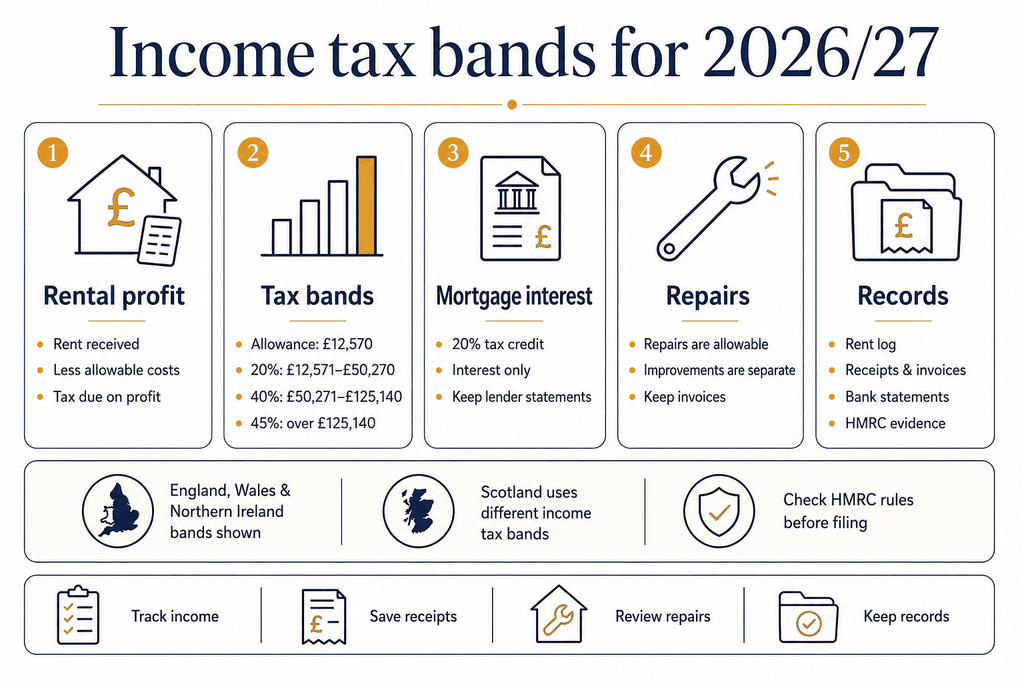
GOV.UK’s Income Tax rates page sets out the current bands and allowances. For landlords in England, rental profit is generally added to other income, so a salary, pension or self-employment income can push property profit into a higher tax band.
This is why two landlords with identical rent can have different tax bills. The rental property does not sit in isolation; it sits inside the owner’s wider tax position.
The practical test is whether another person could pick up the file and understand what happened without phoning the landlord for the story. A clear record should show the date, the reason for the decision, who agreed it, what evidence supported it and what happened afterwards. That level of detail is not bureaucracy for its own sake; it is what turns tax bands from a loose intention into something defensible if the tenancy, tax return, insurance claim or sale later comes under scrutiny. HMRC’s Income Tax rates and allowances and property income guidance should be checked before filing, because the tax position depends on total income and allowable costs, not rent received alone.
A small timing difference can change the practical result. Rent received in one tax year, an invoice paid in another, or an approval notice issued after deductions have started can all affect the figures the landlord needs to report.
This is also where landlords should avoid copying a process from a different property. A leasehold flat above a shop, a family house in Barking, a converted HMO in Newham and a newly bought auction property can all sit under different practical constraints. Mortgage conditions, block rules, council licensing, insurance wording and tenant profile can change what is sensible. A decision that works cleanly for one property can be risky for another, even when the search query looks the same.
Mortgage interest and Section 24
Individual residential landlords no longer deduct mortgage interest in the old way. Instead, finance costs usually generate a basic-rate tax credit, which can make geared property less tax efficient for higher-rate taxpayers.
Before refinancing or buying another property, landlords should model the after-tax return rather than focusing only on gross yield.
Landlords also need to separate the legal rule from the commercial decision. Something can be legally possible but still poor management if it increases void risk, creates a repair dispute, breaches a mortgage condition or makes the property harder to let. Before acting, check the numbers, the paperwork and the likely tenant reaction together. That is especially important in London, where licensing, affordability and property condition can change the outcome of the same decision from one borough to the next. HMRC’s Income Tax rates and allowances and property income guidance should be checked before filing, because the tax position depends on total income and allowable costs, not rent received alone.
Keep agent statements, tenancy agreements, gross-payment approvals, deduction certificates and bank records together. If the landlord changes agent or returns to the UK, those records make it much easier to explain the position without reconstructing years of payments.
The money should be looked at alongside the admin burden. A landlord might save a small amount by handling a task alone, but lose far more if the process creates a void, an invalid notice, a failed claim or a deduction dispute. That does not mean every landlord needs full management. It means the decision should be based on the cost of mistakes as well as the cost of the service.
Repairs, improvements and record keeping
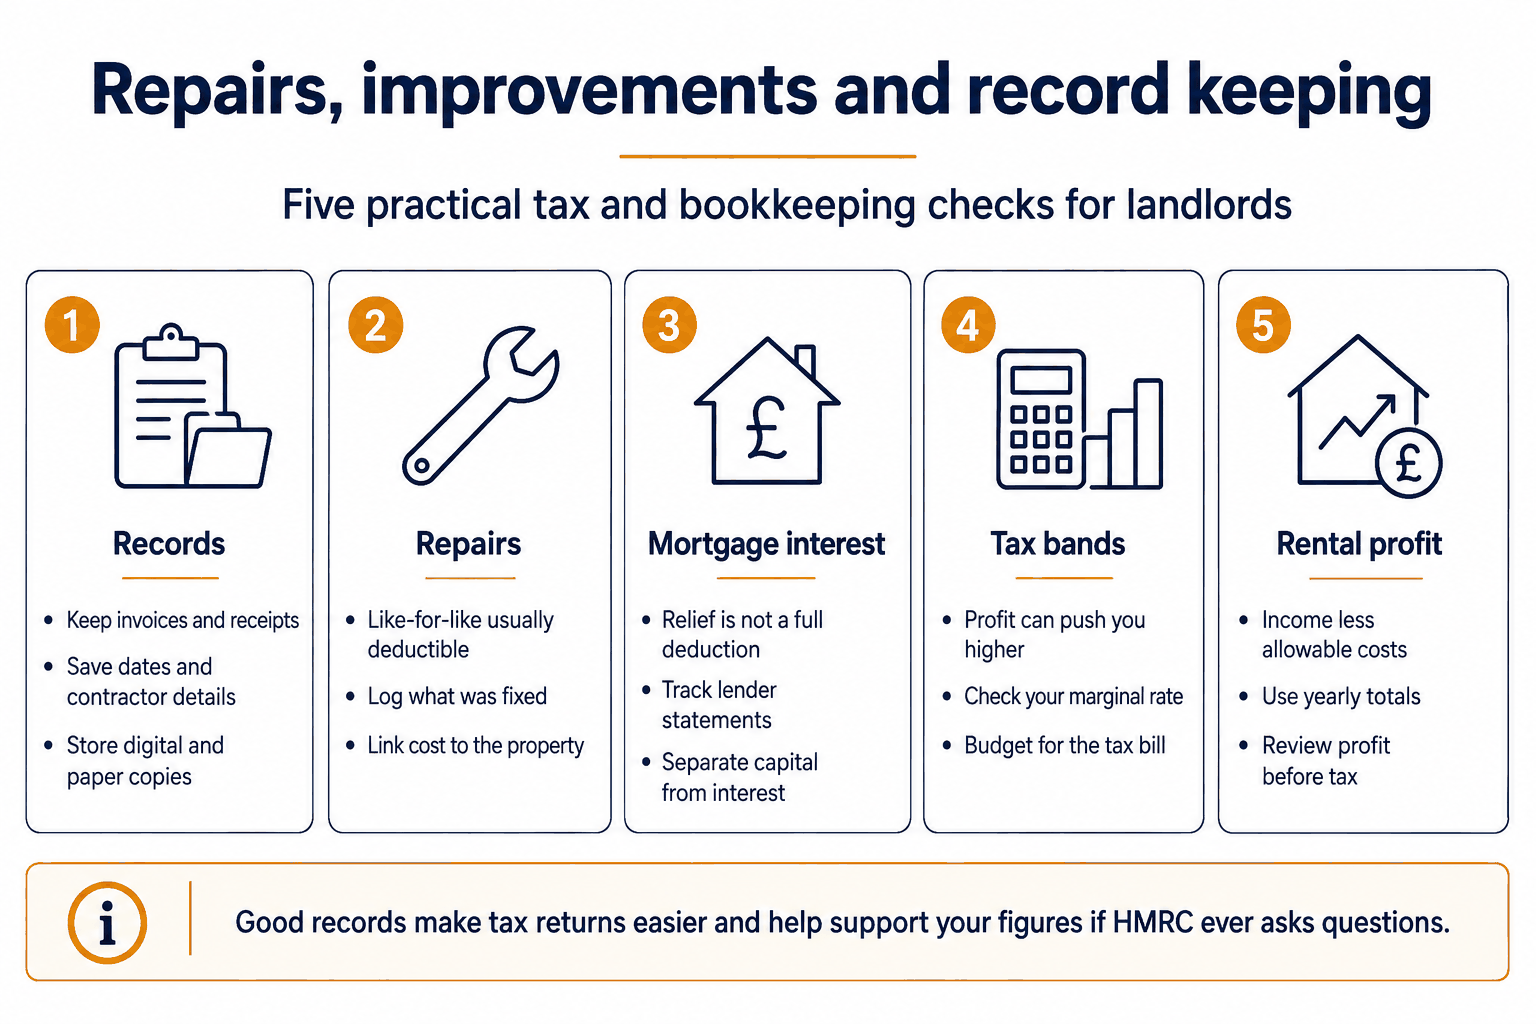
The repair-versus-improvement distinction matters. Repairing a leaking roof is different from extending the roof or upgrading the property beyond its previous condition. Invoices should describe the work accurately, not just say ‘building work’.
Keep invoices, bank statements, tenancy agreements, statements from agents and inspection reports for at least the relevant HMRC record-keeping period. Clean records also help with deposit disputes and insurance claims.
A useful way to approach this section is to think about the end of the tenancy before the beginning. If the tenant leaves, the property is inspected, or a buyer’s solicitor asks questions, the landlord will need proof of what was agreed and why. Photographs, dated emails, contractor invoices, rent records and certificates are often more persuasive than a later explanation. Good record keeping also makes it easier for a managing agent or solicitor to step in without starting from scratch.
Tax planning should be separated from record keeping. The landlord may need an accountant for the planning, but the day-to-day evidence comes from invoices, statements, bank entries and clear notes about whether work was a repair or an improvement.
Tenants also respond better when the position is explained early. Clear move-in documents, prompt repair updates and plain reasons for decisions reduce suspicion and make later discussions easier. Many disputes start because the tenant only sees the landlord’s decision after money is being withheld, rent is being increased or access is being requested. A short written explanation at the right time often prevents the matter becoming formal.
Making Tax Digital and future property tax rates
The government has announced changes to property income tax rates from April 2027, with property rates rising by 2 percentage points. GOV.UK’s property income tax rate change note should be checked when planning future-year forecasts.
Landlords with larger rental income should also prepare for Making Tax Digital obligations by keeping digital records and using software that can handle quarterly submissions when required.
The figures should be tested on a net basis. A headline saving, higher rent, cheaper quote or faster route can disappear once finance costs, compliance work, void periods, tax treatment and repairs are included. Landlords should compare the likely annual position rather than the first monthly figure, and they should update that calculation when the market changes. That gives a more honest view of whether the choice supports reliable income or simply moves risk into a different column.
Where there are several UK properties, each property should have its own income and cost trail. Combining everything into one loose set of figures makes it harder to identify allowable expenses, overseas deductions or the true net return from each address.
The final check is whether the decision still works if circumstances change. A tenant may leave earlier than expected, market rent may move, a repair may reveal a bigger defect, or a council may ask for more information. Good landlord planning leaves room for those changes. It does not assume that the smoothest version of events is the only version that needs to be costed or documented.
Frequently asked questions
Do landlords pay tax on rent or profit?
Tax is generally calculated on rental profit after allowable expenses, not simply the rent received.
Can I deduct mortgage payments?
Capital repayments are not deductible. Mortgage interest relief for individual residential landlords usually works through a basic-rate tax credit.
Are repairs tax deductible?
Repairs can be allowable where they restore the property, but improvements are usually capital in nature.
Do I need an accountant?
It is sensible if you have mortgage finance, multiple properties, overseas residence, joint ownership or large improvement costs.
Will property income tax rates change?
Government guidance says property income tax rates are due to rise from April 2027.
Work from net profit, not rent received
For tax, ownership, overseas landlord or legal questions, use AMS legal and financial property advice alongside advice from a qualified solicitor or accountant.