Table of Contents
Signs the Housing Market Will Crash: What to Watch matters because it can affect money, timing, legal risk and the documents a landlord, tenant, buyer or guarantor may need to rely on later. A quick answer is rarely enough where the property, agreement or deadline changes the outcome.
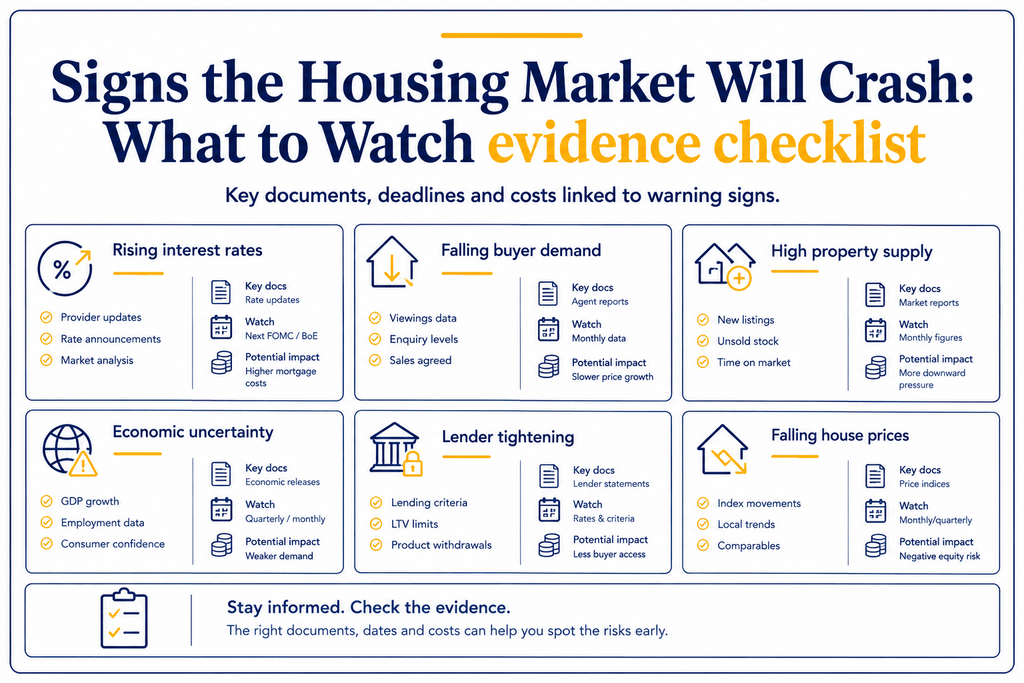
A safer starting point is the written evidence: the agreement, property address, dates, people involved and records already available. Where the topic is controlled by law or official process, official guidance should be read alongside the actual documents rather than used as a substitute for them.
Most mistakes happen when someone treats signs the housing market will crash as a yes-or-no issue. The better approach is to identify the specific property, document, deadline and evidence before deciding what to do next.
House-price falls versus a market crash
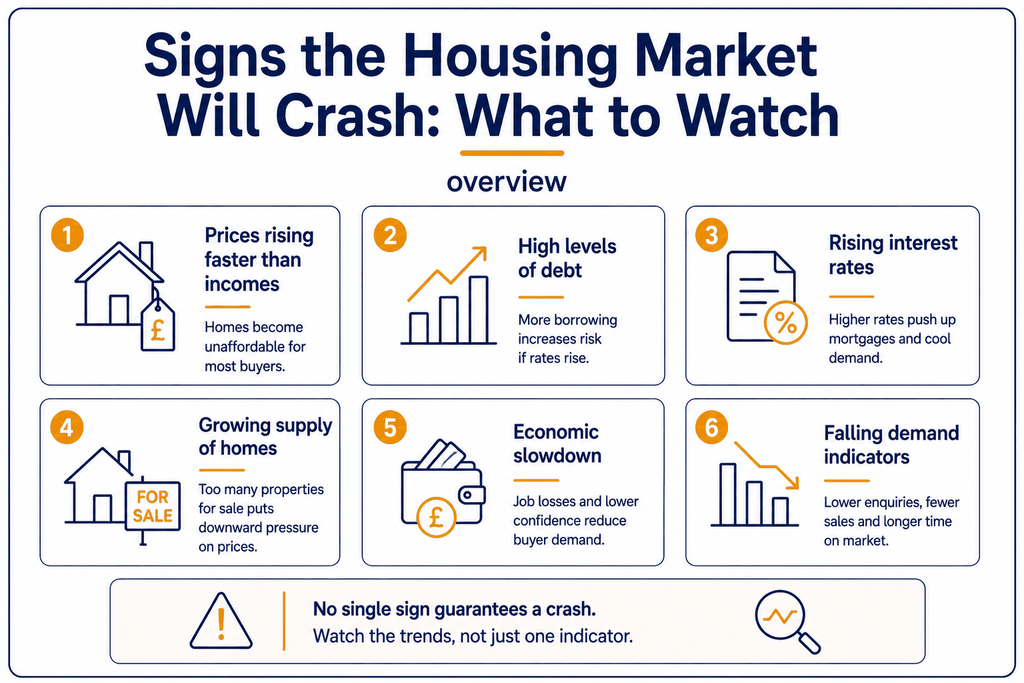
A fall in prices is not automatically a crash; scale, speed and forced selling matter. Landlords should separate media language from measurable signals before changing strategy. What matters is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in ons rents, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with valuation enquiry.
Mortgage rates and buyer affordability
Higher borrowing costs reduce what buyers can pay, especially first-time buyers and leveraged landlords. Affordability pressure can slow sales even when nominal asking prices remain high. The important issue is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The risk often appears in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in ons rents, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with legal and financial advice.
Rent growth and landlord yield pressure
Rents can rise while house prices soften, changing the yield picture. A landlord deciding whether to sell should compare capital value risk with rental income strength. What matters is the connection between the rule and the next decision. When someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. The relevant date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in ons rents, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. The sensible approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with landlord costs.
Supply, listings and time on market
More listings and longer selling times can indicate weaker demand. This signal is more useful locally than nationally because London submarkets move differently. What matters is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in selling a home, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with property sales.
Unemployment, wages and arrears risk
A downturn becomes more serious when household income weakens and arrears rise. Landlords should consider tenant affordability and arrears planning, not only sale prices. The important issue is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The risk often appears in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in ons rents, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with property management.
Policy, tax and landlord exits
Tax and regulation can change supply by making some landlords sell. That can reduce rental supply even while increasing homes listed for sale. What matters is the connection between the rule and the next decision. When someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. The relevant date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in renters rights, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. The sensible approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with guaranteed rent.
What landlords should do before reacting
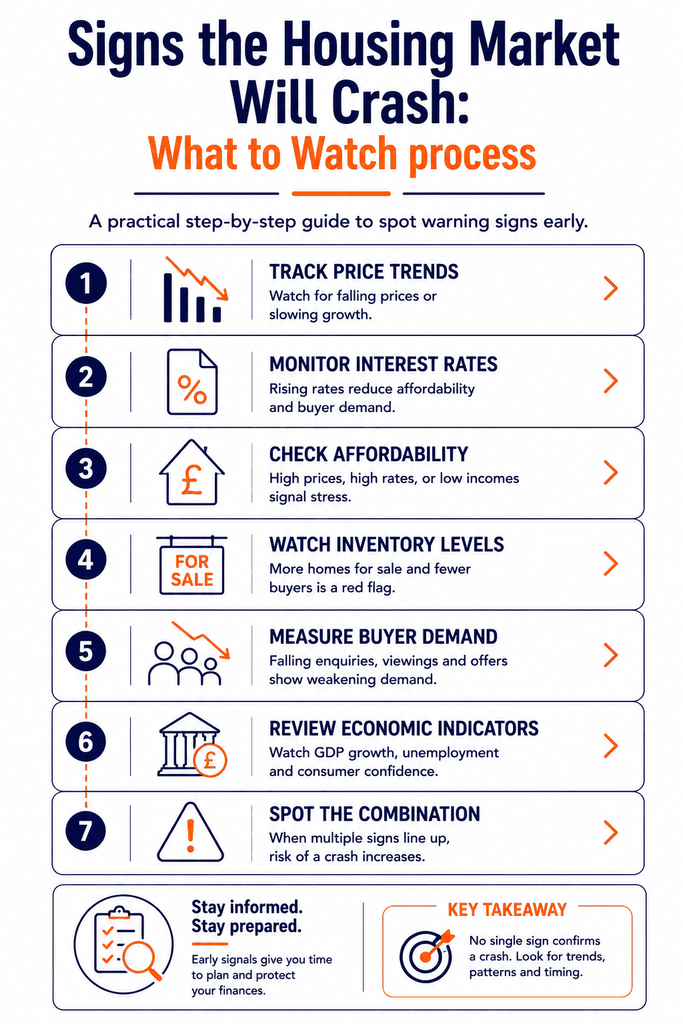
A crash prediction should lead to stress-testing, not panic. Review mortgage renewal dates, cash reserves, rent level, repair commitments and exit value. What matters is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in selling a home, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with valuation enquiry.
Frequently Asked Questions
What is the main thing to know about signs the housing market will crash?
The main point is that signs the housing market will crash depends on the exact property, agreement, dates and evidence. A general answer is useful only when it is applied to the real documents.
Which documents should be checked?
Check the tenancy or contract, certificates, invoices, notices, correspondence, photos, official guidance and any mortgage, lease or insurance conditions.
Can this create financial risk?
Yes. Mistakes can lead to lost rent, delayed sales, tax errors, deposit disputes, repair costs, enforcement action or legal fees.
When should professional advice be taken?
Take advice where the issue affects tax, ownership, possession, safety, licensing, immigration checks, commercial leases or large repair spending.
What to do next
A landlord who wants practical help with the property side of this issue can start with legal and financial advice, request a valuation enquiry, or speak to the team through contact.