Table of Contents
What Happens to a House When the Owner Dies? matters because it can affect money, timing, legal risk and the documents a landlord, tenant, buyer or guarantor may need to rely on later. A quick answer is rarely enough where the property, agreement or deadline changes the outcome.
A safer starting point is the written evidence: the agreement, property address, dates, people involved and records already available. Where the topic is controlled by law or official process, official guidance should be read alongside the actual documents rather than used as a substitute for them.
Most mistakes happen when someone treats what happens to a house when the owner dies as a yes-or-no issue. The better approach is to identify the specific property, document, deadline and evidence before deciding what to do next.
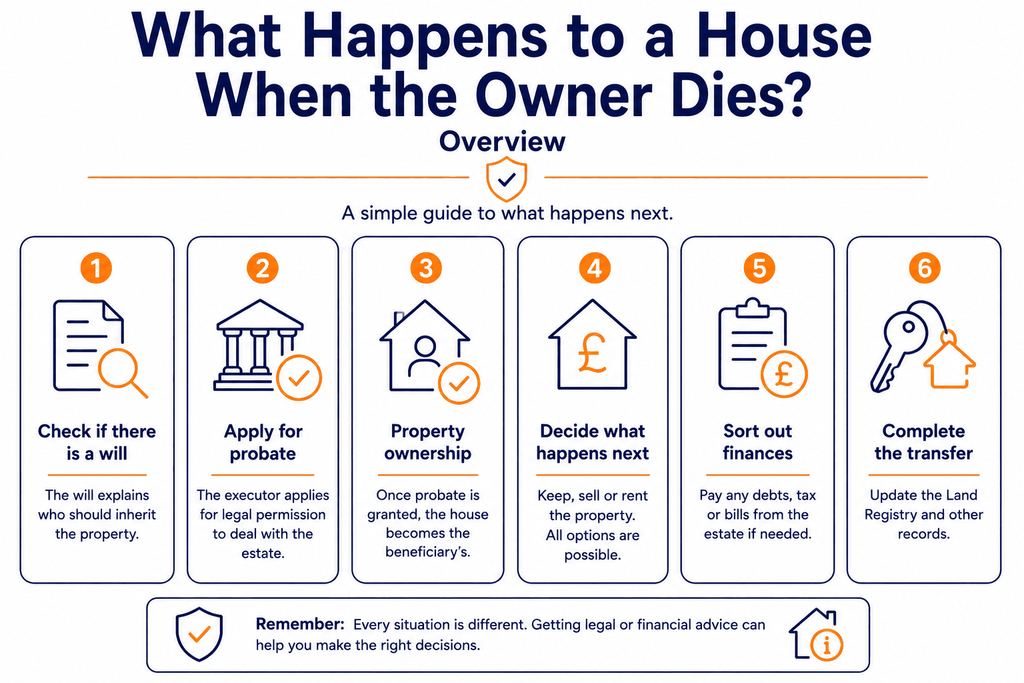
Sole ownership and probate
If the deceased owned the house alone, the estate usually needs authority before sale or transfer. Probate can affect timing for buyers, tenants and beneficiaries. What matters is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in probate, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with property sales.
Joint tenants versus tenants in common
The form of co-ownership can decide whether the property passes automatically or through the will. The title register and any trust documents should be checked. The important issue is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The risk often appears in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in probate, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with legal and financial advice.
Mortgage payments and insurance
The mortgage and insurance position should be addressed quickly after death. Missed payments or invalid cover can create avoidable loss. What matters is the connection between the rule and the next decision. When someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. The relevant date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in probate, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. The sensible approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with legal and financial advice.
If the property is rented out
A tenancy does not automatically disappear because the landlord dies. Rent collection, repairs and notices need to be managed by the right person. What matters is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in landlord responsibilities, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with property management.
Selling an inherited property
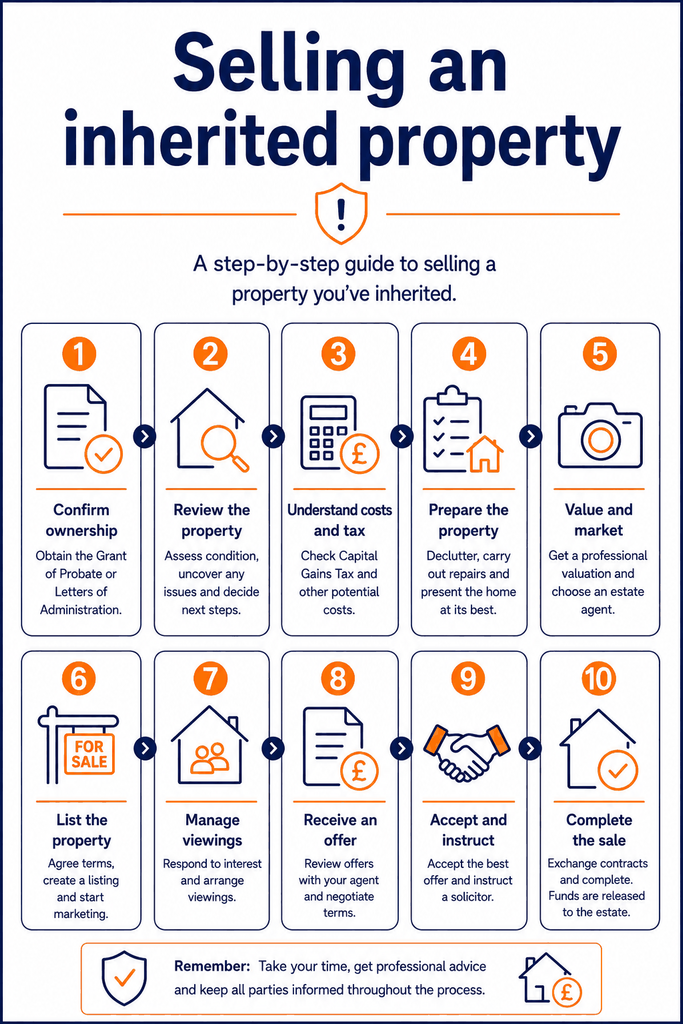
Selling can involve probate timing, clearance, valuation, tax and buyer due diligence. A rushed sale can reduce value if paperwork is missing. The important issue is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The risk often appears in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in selling a home, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with property sales.
Capital Gains Tax and inheritance records
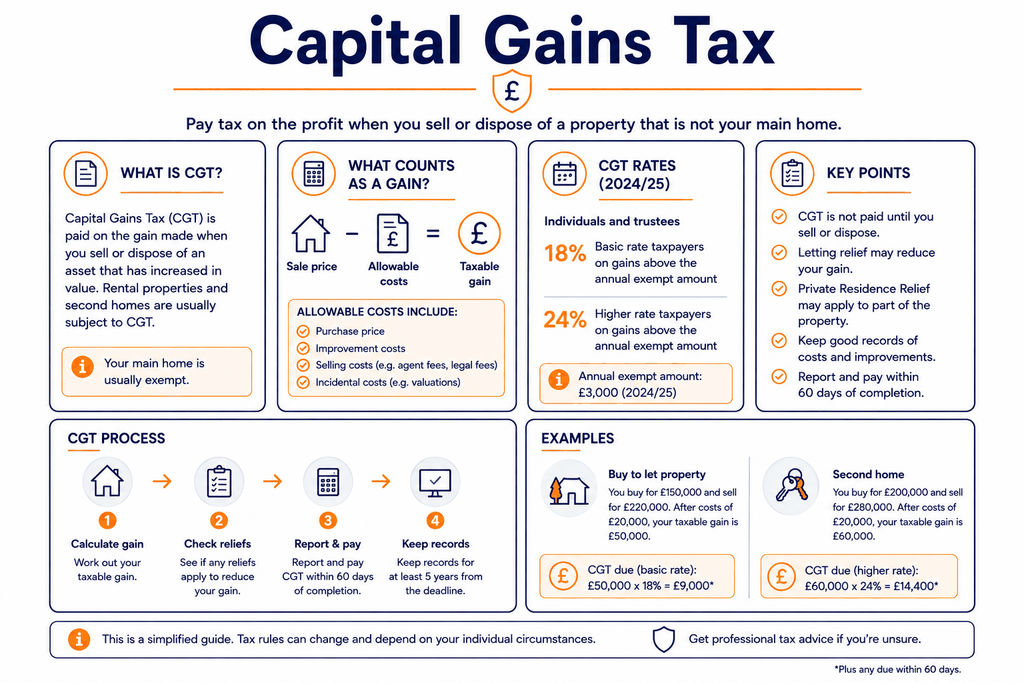
Beneficiaries should record probate value, sale price and costs. Tax may arise if the property increases in value after death. What matters is the connection between the rule and the next decision. When someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. The relevant date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in cgt property, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. The sensible approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with landlord tax guide.
When an attorney or executor needs help
An attorney or executor may need practical management support as well as legal authority. Repairs, insurance and tenant communication still need attention. What matters is the connection between the rule and the next decision. If someone is letting, selling, refinancing, evicting, improving or changing how a property is occupied, the supporting evidence needs to exist before money is spent or notice is served.
The practical risk usually sits in the gap between a simple answer and the evidence needed to prove it. A date, certificate, invoice, tenancy clause, consent letter or council licence can decide whether a landlord is protected. Without that evidence, a reasonable decision can become difficult to defend later. The official position is set out in lpa, which is why the detail should be checked before relying on an old blog post, template or forum answer.
In London and Essex, the local detail can change the cost and timing of a decision because values, rents, leasehold rules, licensing schemes and contractor costs are rarely modest. A small delay can affect a sale timetable, rent collection, tenant relationship or tax bill. A safer approach is to decide what has to be checked, who is responsible for checking it, and where the record will be stored before the next step is taken. Landlords who want the issue handled as part of a wider property plan can compare this with property management.
Frequently Asked Questions
What is the main thing to know about what happens to a house when the owner dies?
The main point is that what happens to a house when the owner dies depends on the exact property, agreement, dates and evidence. A general answer is useful only when it is applied to the real documents.
Which documents should be checked?
Check the tenancy or contract, certificates, invoices, notices, correspondence, photos, official guidance and any mortgage, lease or insurance conditions.
Can this create financial risk?
Yes. Mistakes can lead to lost rent, delayed sales, tax errors, deposit disputes, repair costs, enforcement action or legal fees.
When should professional advice be taken?
Take advice where the issue affects tax, ownership, possession, safety, licensing, immigration checks, commercial leases or large repair spending.